Cardano Is Coming to AI Payments
An AI assistant can write a report, compare suppliers, or help build an application. But when completing a task requires buying fresh data or paying another service, it often runs into a familiar obstacle: someone needs to create an account, arrange billing, and approve access.
That becomes awkward when software needs to work across many independent providers. A research agent might need one dataset from one company, a document analysis from another, and a specialist calculation from a third. Setting up three subscriptions for a single assignment is a poor fit.
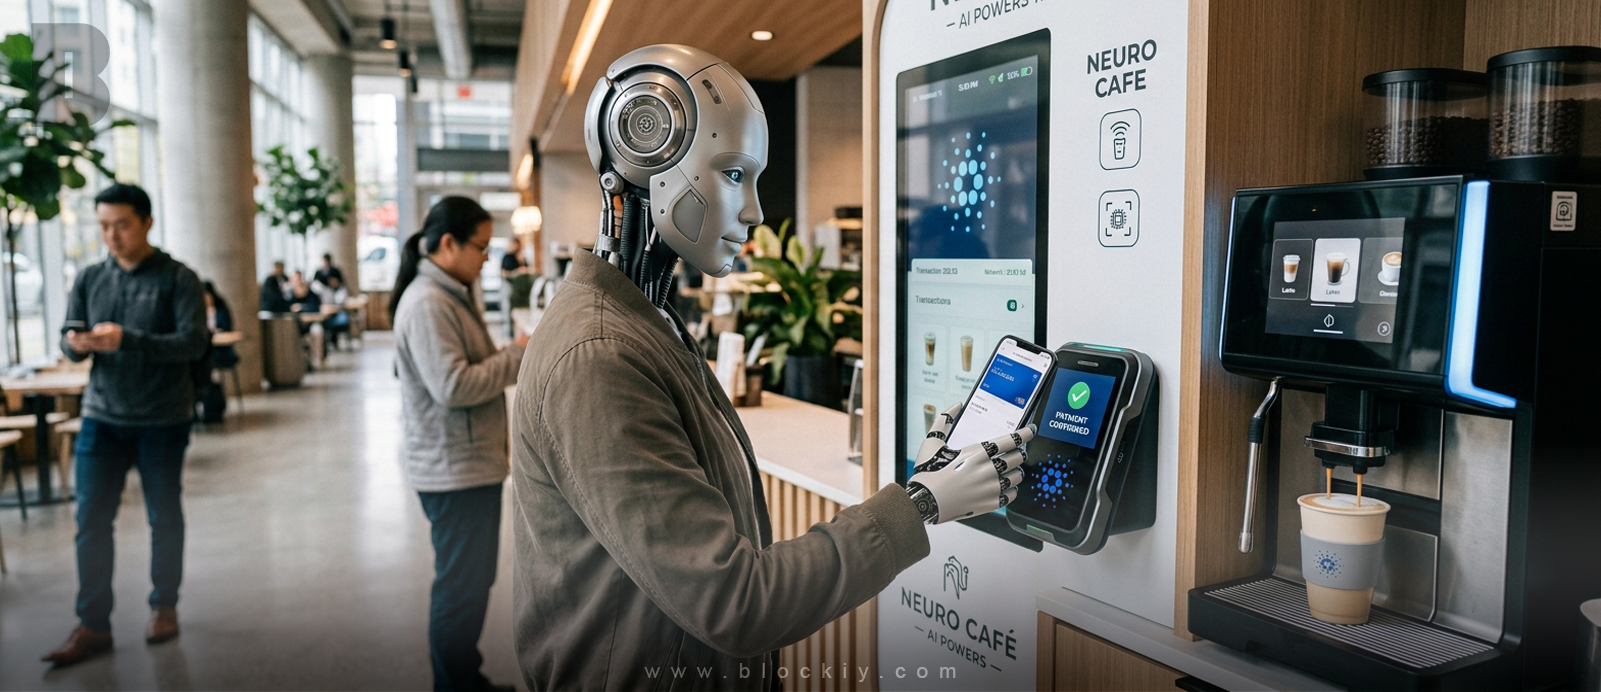
Machine-readable payments offer another approach. A service publishes its price, the agent checks whether the purchase fits its permissions and budget, and a payment unlocks the next step.
Cardano is entering that market through x402 payment support and an emerging ecosystem of agent infrastructure, including Masumi. Some building blocks already exist. The commercial question is how widely they will be used, and whether they make buying digital services easier and more economical.
For Cardano, the opportunity is a new category of customers: software purchasing services on behalf of people and businesses. Understanding that opportunity requires looking beyond the announcement to the complete payment experience.
What Has Actually Changed?
The official x402 repository includes a Cardano payment scheme. Cardano’s AI ecosystem also includes Masumi for agent payments and identity, with marketplaces such as Sokosumi providing a way to discover and hire agents.
These components address related parts of a larger problem: how software discovers a service, agrees to its terms, pays for it, and keeps a record of the interaction.
A published payment scheme is meaningful because it gives developers a shared way to describe transactions. However, a specification, a compatible implementation, and a commercially successful service are different milestones. Providers still need working integrations, supported assets, reliable operations, and paying customers.
There is also no universal switch that makes every AI assistant use Cardano. A developer must connect the payment functionality, and the service being purchased must accept the relevant payment option.
What Are AI Payments?
An AI payment is a payment initiated or coordinated by software performing a task under delegated authority.
The money still belongs to a person or organization. The agent is given limited permission to spend it, much like an employee purchasing a service within an approved budget.
Consider a hypothetical logistics assistant preparing a delivery plan. It might purchase current road restrictions, request a route calculation, and pay for a specialist forecast. The value comes from completing the assignment without requiring a human to arrange every small purchase.
This does not require unrestricted autonomy. A business could allow small purchases from approved providers while requiring human approval for anything expensive or unfamiliar.
The useful progression is from software that recommends an action to software that can complete an authorized action, including its payment.
How x402 Makes a Web Request Payable
x402 is an open payment standard that can use HTTP 402, the web response code meaning “Payment Required.” It lets a service communicate payment terms in a form that software can process.
A typical interaction works like this:
- An agent requests a paid resource, such as a dataset.
- The service returns payment requirements, including the amount, recipient, network, and accepted asset.
- The client checks the offer and signs a supported payment.
- It sends the request again with the payment information attached.
- The service verifies the payment authorization, often through a facilitator.
- The requested work is performed, payment is submitted for settlement, and the response is returned under the integration’s rules.
A facilitator handles payment verification and settlement for the service. It remains an operational dependency even when it does not hold the customer’s funds.
This can remove a separate checkout process for supported services. Providers may still require identification, access controls, or contractual terms where their product calls for them.
Where Masumi Fits
Payment is only one part of hiring an agent. Buyers also need to identify the provider, describe the job, and understand what happens if delivery fails.
Masumi addresses agent payments and identity, with registry and payment services and mechanisms for recording cryptographic evidence associated with outputs. Its tooling can help connect independently developed agent services.
Cardano’s x402 scheme distinguishes direct payments, Masumi escrow payments, and payments to other scripts. These choices have different consequences for the buyer.
A direct transfer pays the recipient. An escrow arrangement locks funds under contract rules governing their later release, refund, or dispute. In the Masumi route, x402 covers the initial lock; the subsequent lifecycle belongs to the contract and associated payment services.
Refund protection therefore depends on the selected payment method and its rules. It is not a universal feature of every x402 transaction.
For a buyer, the practical questions are straightforward: What counts as delivery? When can the provider claim payment? Who can challenge the result? What must happen to recover funds?
Paying an Agent Does Not Prove Its Answer Is Correct
Suppose an agent buys a report about a company’s competitors. The payment settles correctly, and a document arrives on time. The report could still contain outdated prices or invented claims.
Blockchain settlement can establish facts about the payment. A cryptographic hash can help establish whether a document matches a previously recorded version. Neither automatically establishes that the document is accurate.
An escrow contract also needs defined evidence and conditions. It cannot independently judge every aspect of a marketing plan, software review, or financial forecast.
A useful service should therefore specify its deliverable before accepting payment: the required fields, data freshness, completion deadline, acceptable format, and failure procedure. For consequential work, human review may remain part of the process.
This is where product design becomes as important as payment engineering. Buyers need to know what they are purchasing and what remedy exists when the result falls short.
What Could Businesses Actually Build?
The strongest early opportunities are likely to be narrow services with clear outputs and measurable value. The following are illustrative business models, rather than claims that every example is already operating on Cardano.
| Service | What an agent purchases | What the buyer can check |
|---|---|---|
| Document extraction | Structured data from a supplied file | Required fields, format, and extraction accuracy |
| Specialist data access | A current dataset or individual lookup | Coverage, timestamp, and usage rights |
| Code analysis | A review of a defined code change | Findings tied to files and reproducible checks |
| Translation | A specified document in a target language | Completeness, terminology, and formatting |
| Infrastructure monitoring | An assessment of a defined system | Observation period and supporting measurements |
A specialist provider could charge per completed job instead of asking every customer to maintain a subscription. An agent could choose that provider when its capabilities fit the task.
Subscriptions would still make sense for predictable, high-volume relationships. Payments per request become more attractive when demand is occasional, providers vary, or customers need a small piece of a larger service.
For a Cardano analytics business, one possible product would be a paid historical pool report with a defined time range and structured output. An external agent could purchase it as part of a broader analysis. Its commercial appeal would depend on the quality and uniqueness of the information.
Why Cardano Could Be Useful for This Model
Cardano’s extended UTXO model offers useful properties for automated payments. Transactions consume specific unspent outputs and create new ones, allowing much of their validity and cost to be assessed before submission.
For an automated buyer, this supports a sensible control: inspect the transaction before authorizing it and confirm that its recipients, amounts, and expected costs match the purchase.
There is an engineering trade-off. If several workers try to spend the same output, their transactions conflict. A busy agent service needs coordinated transaction construction and sufficient available outputs for parallel spending.
Cardano also supports native assets, allowing payment products to use assets other than ADA where the integration accepts them. A provider can choose pricing and settlement arrangements suited to its customers.
These features create options for developers. Adoption will depend on the complete service being reliable, affordable, and easy to integrate.
Small Payments Need Careful Economics
The phrase “AI micropayments” can hide a difficult business problem. A tiny purchase may be technically possible while still being uneconomical to settle individually.
Cardano transactions carry network fees. Those fees depend on transaction construction and applicable protocol parameters; script interactions can add further costs. Network costs sit alongside compute, storage, service-provider charges, and any currency conversion.
Consider a hypothetical service charging $0.01 per query. If its total settlement overhead were $0.04 per query, processing 1,000 individually settled queries would generate $10 of sales against $40 of settlement costs, before paying for the service itself. Those numbers illustrate the calculation; they are not current Cardano fee quotes.
Possible designs include selling a bundle of queries, charging per completed task, or using an appropriate batching or payment-channel arrangement. Each changes the experience and may introduce additional assumptions.
Developers need to measure the cost of a complete successful job. Counting only the advertised payment amount leaves out the expenses that determine whether the product can survive.
The Infrastructure Behind Automated Payments
An automated customer may retry immediately when a service fails. A small outage can therefore become a burst of repeated requests, uncertain payments, and support problems.
A dependable payment product needs reliable blockchain access, transaction tracking, application monitoring, and recovery procedures. It should reconcile its own records against settlement outcomes after interruptions.
Stake pools support Cardano’s underlying block production. Application servers and payment facilitators perform different jobs above that network. An AI payment business can use Cardano without operating a stake pool.
For teams that also want to participate in network infrastructure, Blockiy’s Professional Cardano Stake Pool Setup Service provides a place to request a professionally configured Cardano staking pool.
That is a separate operational commitment. A pool needs ongoing maintenance and sufficient delegated stake to have a meaningful prospect of producing blocks; launching one does not automatically generate AI service revenue.
Settlement Speed Must Match the Product
Signing a payment, submitting it, and confirming it are different events. Cardano’s payment scheme makes confirmation policy explicit; acceptance into a node’s transaction queue is not equivalent to a confirmed payment.
That distinction matters when the product is delivered immediately. Once a seller releases valuable data, it may have no way to recover it if payment does not complete.
The right design depends on what is being sold. A report that takes several minutes to generate has different timing requirements from a tool used inside an interactive conversation. Measure the entire journey from request to usable result, including the provider’s work and payment processing.
If a system uses an additional scaling layer, its performance needs to be assessed within that system’s actual operating conditions. A faster payment architecture should be evaluated together with its liquidity, availability, and recovery requirements.
Agents Need Spending Limits Outside the Model
An instruction such as “do not spend more than $10” is useful guidance, but it should not be the only control protecting a wallet.
Language models can misunderstand requests or encounter malicious instructions embedded in external content. An agent researching a website should never gain permission to move funds simply because the website tells it to.
A safer architecture lets the model propose a purchase while a separate policy and signing component decides whether it is allowed.
Useful controls include:
- A maximum amount per purchase and per day.
- Approved providers and payment destinations.
- An explicit list of accepted networks and assets.
- Human approval above a chosen threshold.
- Limits on repeated purchases and retries.
- A small operational balance separate from treasury funds.
- A way to stop spending immediately.
These controls should apply to the complete transaction, including fees and additional outputs. A displayed service price alone does not describe everything a signature authorizes.
Failures and Refunds Belong in the Product Design
Imagine an agent pays for a document conversion, but its connection drops before the response arrives. It retries. Should it pay again, receive the original result, or wait for confirmation?
The service needs an answer before launch.
Each order should have a durable identity that connects the request, payment, processing status, and result. Repeating the same operation should not silently create a new charge.
A payment product should also distinguish a rejected payment from one that is still pending. Treating every timeout as failure can cause duplicate purchases even when the first payment eventually succeeds.
Refunds need equally clear terms. Buyers should know which failures qualify, who initiates the process, how long it takes, and whether network costs are recoverable. An escrow mechanism helps only when the surrounding application implements its lifecycle correctly.
Privacy Still Matters When Software Is the Customer
An agent may handle invoices, private documents, customer records, or internal code. Recording a payment publicly does not mean the underlying material should also become public.
A sensible design separates the settlement record from the confidential job content. Sensitive files should remain in appropriately protected storage, with access limited to the services that need them.
Even a hash requires thought: if the original information is easy to guess, publishing its hash can reveal more than expected. Public payment patterns can also expose relationships between buyers and providers.
For a business customer, privacy and retention rules are part of the purchasing decision. A technically convenient API is not enough if the company cannot explain where its data goes.
What Could AI Payments Mean for ADA?
The possible benefit to Cardano is additional economic activity: services accepting payments, businesses integrating wallets, and developers maintaining useful products on the network.
ADA remains relevant to base-layer transaction fees even when the purchased service is priced in a supported native stablecoin. A product may arrange those fees on behalf of the end user.
However, more activity does not produce a fixed or automatic increase in ADA’s price. A business may maintain only a modest working balance. Batching can reduce transactions per job. Market conditions and the scale of actual demand also matter.
The same caution applies to staking rewards. A pool does not receive the individual fee from each AI payment it includes as a separate direct commission. Cardano pools fees within its broader reward mechanism.
The useful investment question is whether paying customers repeatedly choose services that settle on Cardano. A busy, sustainable market would provide stronger evidence than an integration announcement alone.
How a Developer Could Test the Opportunity
A focused pilot can answer more than a large launch built around an uncertain customer need.
- Choose one useful service. Define a specific deliverable, buyer, and reason to pay.
- Set the terms. Specify the price, asset, deadline, output format, and failure policy.
- Check compatibility. Confirm that the client, server, wallet, and facilitator support the intended Cardano payment method.
- Test without real customer funds. Exercise success, rejection, timeout, duplicate requests, and interrupted processing.
- Measure the economics. Include settlement, compute, storage, refunds, and support in the cost per completed job.
- Launch with limited exposure. Start with low spending limits, a small customer group, and clear monitoring.
- Evaluate repeat demand. Check whether customers return after the novelty wears off.
The first commercial milestone is a customer paying again because the output helped them finish real work.
What Would Prove This Is Working?
Announcements and registered agents are useful indicators of interest. They do not establish a functioning market by themselves.
Better measures include:
| Metric | What it helps establish |
|---|---|
| Completed paid jobs | Whether services are delivering actual work |
| Repeat paying customers | Whether buyers find lasting value |
| Successful jobs after refunds | Whether reported activity survives delivery problems |
| Cost per completed job | Whether the business model is economical |
| Time from request to usable result | Whether the experience fits the customer’s task |
| Independent buyers and providers | Whether activity extends beyond a small affiliated group |
| Revenue after incentives | Whether demand persists without subsidies |
These measures need context. One company can run many agents, and one customer can control many wallets. Transaction counts should not be presented as customer counts.
What Comes Next for Cardano AI Payments?
Cardano now has concrete payment standards and agent infrastructure around which developers can build. The next challenge is making those components disappear into a dependable customer experience.
A business should be able to give an assistant a defined assignment and budget, understand which providers it used, inspect what it received, and account for every payment. Providers should be paid predictably for useful work, with manageable costs and clear handling of failures.
That is a demanding product problem, but it is also a credible opportunity. If Cardano can make these transactions practical across independent services, AI payments could bring recurring activity from customers who care primarily about getting work done.
The strongest evidence will be ordinary: useful services, completed jobs, satisfied buyers, and another payment when the next task arrives.